Your Local Mortgage Lender
Located in Woodland Hills, California
Personalized Mortgage Experience
George Youhana offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Woodland Hills, California.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
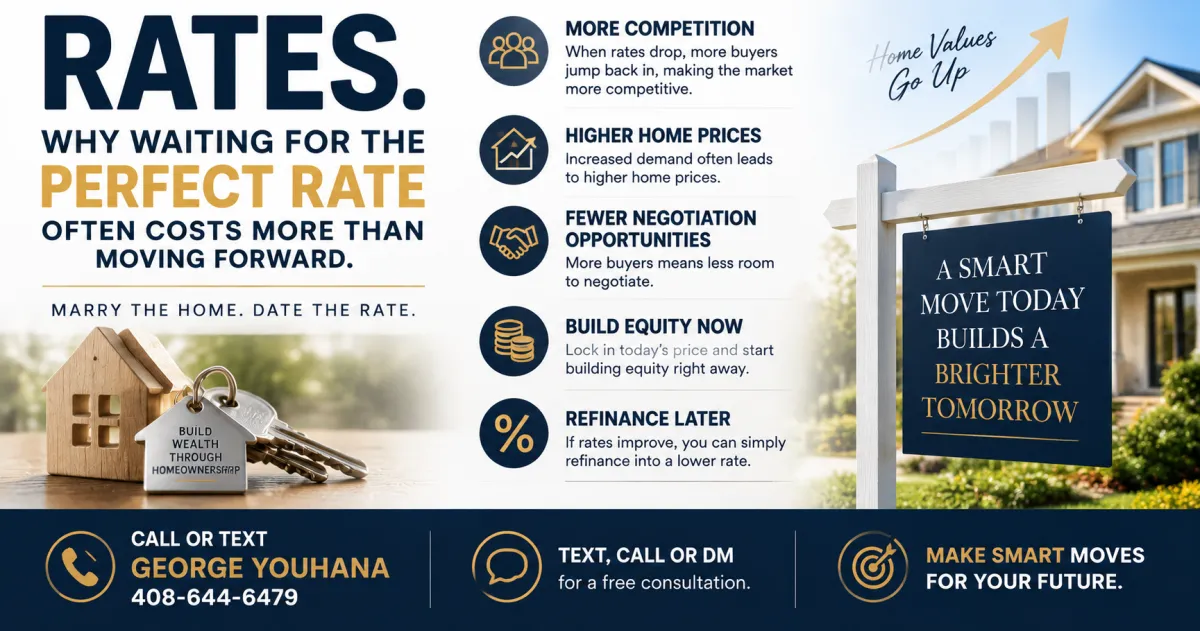
Waiting for the Perfect Mortgage Rate Often Costs More Than Moving Forward and Here Is Why
Waiting for the Perfect Mortgage Rate Often Costs More Than Moving Forward and Here Is Why
The Question George Youhana Hears From Almost Every Buyer Right Now
Should I wait for rates to drop before I buy? It is one of the most common questions buyers are asking and it deserves a clear and honest answer rather than a reassuring non-answer.
The truth is that waiting for the perfect rate often costs more than making a smart move today.
What Actually Happens When Rates Drop
The assumption behind the waiting strategy is logical on the surface. Rates come down. The payment gets more affordable. The buying decision gets easier. What the strategy misses is what happens to the market at the exact moment rates improve.
The buyer pool jumps back in aggressively. Every buyer who was sitting on the sidelines waiting for the same signal decides to act at roughly the same time. More buyers competing for the same available inventory means more competition. More competition means higher home prices. Bidding wars return. Negotiating opportunities that exist right now disappear. The payment savings from the lower rate get partially or entirely offset by the higher purchase price required to win in a more competitive environment.
The buyer who waited does not necessarily end up ahead. They often end up paying more for the home and competing harder just to get it.
The Strategy That Actually Works
Marry the home and date the rate. It is one of the most practical frameworks available in the current market and it changes how the entire rate question should be approached.
The home you purchase today locks in today's price. That price does not change after closing. The equity you build from day one is real and it compounds over time regardless of what rates do. When rates eventually improve you refinance into a lower rate on the loan you already have at the price you already locked in.
You captured today's price. You benefit from the rate improvement when it arrives. And you started building equity during the period when other buyers were still waiting.
What Real Estate Has Always Rewarded
Real estate has historically rewarded action, patience, and long-term thinking. Not perfect timing. The buyers who consistently build wealth through real estate are not the ones who caught the exact bottom of a rate cycle. They are the ones who bought when the decision made sense for their situation, held the asset through normal appreciation, and refinanced when the opportunity presented itself.
Running the Numbers With Total Clarity
As George Youhana explains the goal is not to find the best rate advertised online or to wait for a market signal that may not arrive on the schedule you were hoping for. The goal is to make a smart and informed decision based on your specific situation with full clarity about the numbers.
Call or text George Youhana anytime for a free consultation at 408-644-6479. Follow along for more tips that help you make smart moves with your money.
Sources
NAR.realtor
MortgageNewsDaily.com
FederalReserve.gov
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
